FP&A reforecast cadence lags the AI tools now running it
Midsize finance teams adopted AI for planning in about two years, but most still reforecast on a quarterly rhythm built for manual consolidation. The gap is now a governance problem CFOs own.
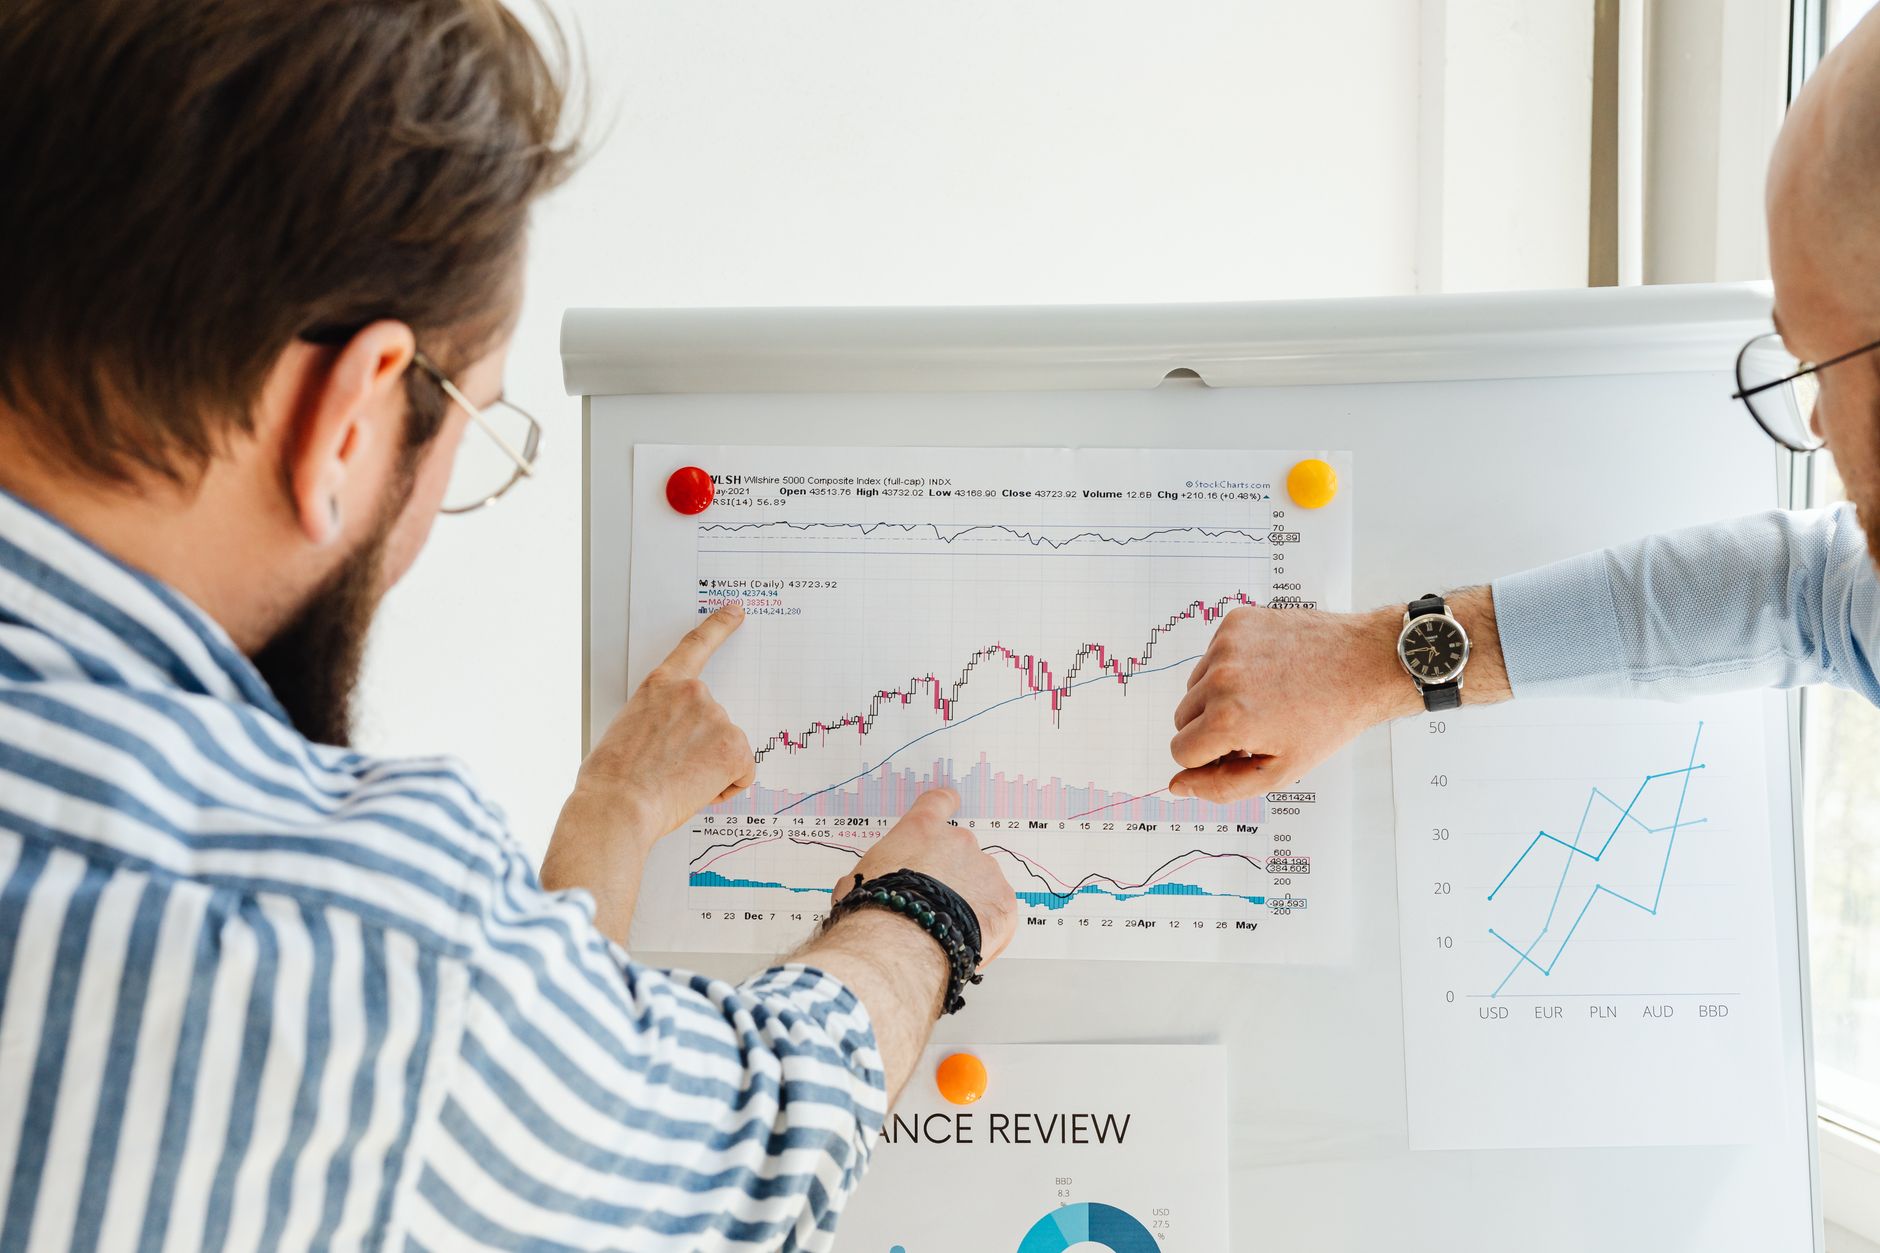
Planning, forecasting, and analysis.

Midsize finance teams adopted AI for planning in about two years, but most still reforecast on a quarterly rhythm built for manual consolidation. The gap is now a governance problem CFOs own.

Aggregate CFO sentiment held steady in the third quarter, but small and financially constrained firms weakened, and a single blended driver set will overstate volume in exactly the segments that break first.

Inference, support agents and embedded copilots are migrating from fixed IT opex into cost of revenue, breaking the margin models FP&A teams are using to lock their 2027 plans.

AI, cloud consumption and growth-function headcount are the fastest-moving lines in the plan, and none of them have a representative prior-year actual to grow off.

CFOs are asking planning teams to fund expansion and hit savings targets inside the same 2027 budget, and after two years of tooling purchases the FP&A stack is now a line item too.

The CFO Survey shows tariff-exposed firms internally modeling growth close to 1.6% while the broad sample edges toward 2.1%, which makes a single house macro assumption a planning defect.

Automation has moved quickly through the close and reporting, but planning teams are holding the line - because a forecast carries judgment and accountability that a reconciliation does not.

The Q2 2026 Duke-Fed CFO Survey shows two-thirds of firms facing higher unit costs from the oil spike, but only one-third have raised prices, leaving gross margin as the shock absorber.

Multi-year compute minimums and prepaid AI credits behave like unfunded purchase obligations, draining operating cash flow quarters before any productivity case becomes provable on the income statement.

Post-midterm legislatures convene in January, and ASC 740 books a rate change in the quarter of enactment, not the year it takes effect. That makes a March signature a Q1 2027 earnings event.

The SEC's proposal to overhaul executive compensation disclosure arrived while calendar-year filers were already scoping CD&A and pay-versus-performance work for spring 2027 proxies.